

Western Union Send Money Now
by Western Union Apps
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
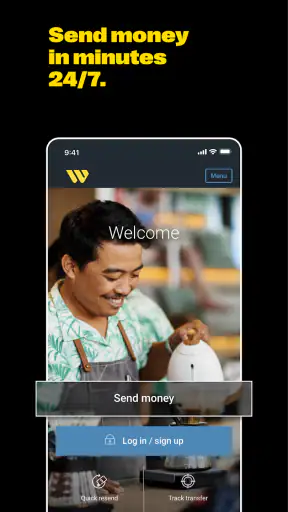
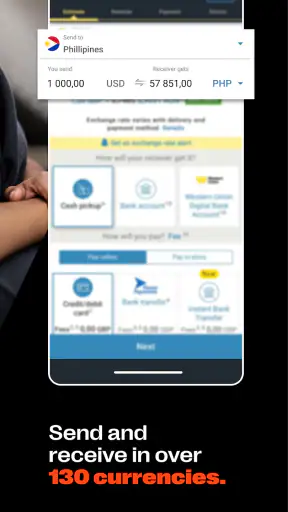
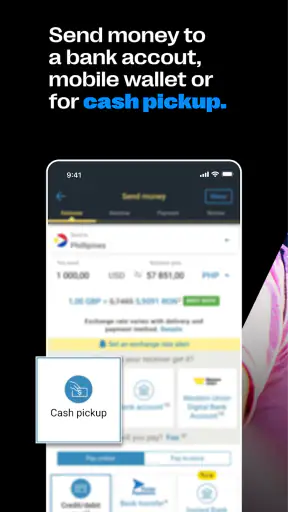
 Analysis by Getfullapps
Sending money across borders is the kind of task I want to finish quickly, clearly, and without wondering whether I missed an important step. Western Union Send Money Now is a finance app from Western Union Apps that puts international transfers into a mobile workflow. I found its strongest appeal during the first use: the app gives a familiar place to begin a transfer, enter recipient details, review the transaction, and keep the process moving without needing to visit a physical location.
That convenience matters most when the transfer is part of a real routine rather than a one-off experiment. I can imagine using it to help family members abroad, send money for an urgent household expense, or manage a recurring remittance while away from home. The app is free to install, carries an Everyone age rating, and supports devices running Android 8.0 or later. Its current version is 16.4, so it is aimed at a broad range of Android users rather than only people with the newest phones.
My overall impression is positive, but not blindly enthusiastic. The app earns a place on my phone when I regularly send money internationally and value the convenience of handling the process myself. It is less compelling for someone who rarely transfers money, dislikes checking transaction details carefully, or already has a cheaper and simpler option through a bank or another transfer service. The important question is not whether it works once; it is whether the workflow remains useful month after month.
What the first week feels like
The first-week appeal comes from having the transfer process available wherever I am. Instead of treating an international remittance as a separate errand, I can approach it as a normal mobile task. That shift is especially useful when timing matters. If a relative messages me about an unexpected bill, I can start the transfer while I have the information in front of me rather than postponing it until I reach a computer or a service counter.
I would still prepare before opening the app. The recipient’s name and payment details need to be entered carefully, and I would keep the recipient’s information nearby rather than relying on memory. A money-transfer app is not the place to rush through spelling or numbers. The convenience of a phone does not remove the responsibility of checking who will receive the money and how the transaction is being sent.
What I appreciate in a first session is the sense of a guided financial task rather than a general-purpose banking dashboard. The app is focused on sending money and remittances worldwide, so its purpose is easy to understand. That focus can make it more approachable for a family member who does not want to learn a full banking application just to complete an international transfer.
There is also a practical psychological benefit to reviewing everything on one screen before committing. I prefer to pause at the final review stage and read the recipient, amount, and transfer details again. My useful habit here is simple: I treat the review screen as a checklist, not as a formality. I do not tap through it while distracted, and I avoid starting a transfer when I cannot give the details my full attention.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The app’s broad adoption gives it a reassuring starting point. It has more than ten million installs, an average rating of 4.7 from roughly 348 thousand ratings, and about 152 thousand written reviews. Those figures do not guarantee that every transfer will feel effortless, but they suggest that the mobile experience is established enough to be familiar to many people. I would still judge it by my own recipient, destination, and payment needs rather than by popularity alone.
A realistic everyday use case
Imagine that I live in one country while my parents live in another. Every month, I send money for groceries and a utility bill. In the first month, I would use the app slowly, confirming the recipient details and saving a personal note outside the transaction if I needed a reminder about the purpose. Before sending, I would compare the amount I intend to send with the amount my family expects to receive, because the two figures can be affected by exchange and transfer conditions.
On a later occasion, an urgent request arrives during a workday. The value of the app is not that it makes financial decisions for me; it shortens the distance between deciding to help and beginning the transfer. I can open the same mobile tool, repeat the familiar workflow, and review the details before confirming. That is the kind of recurring value that survives beyond the novelty of installation.
For a first-time user, I recommend completing a small, non-urgent transfer only after reading every displayed detail. The goal is not merely to test the buttons. It is to learn how the app presents the recipient information, the amount, and the transfer summary so that a future urgent transaction does not become the first time you see those screens.
Where it differs from ordinary alternatives
Compared with visiting a physical agent, the app offers privacy and convenience. I do not need to organize my day around a location, and I can begin the process from home or while travelling. That is a meaningful advantage for people who send money outside normal errands. The trade-off is that the user must be comfortable entering information and following the digital process without someone beside them.
Compared with a bank’s mobile app, Western Union Send Money Now is more narrowly centered on remittances. A bank app may be better if I want transfers, account balances, bill payments, and everyday banking in one place. Western Union’s focused purpose can be easier for a dedicated international transfer, but it does not replace a complete banking relationship.
Compared with newer digital transfer services, the deciding issue is rarely the appearance of the app alone. I would compare the final amount, available delivery choices, speed, and convenience for the specific destination. A service that looks modern is not automatically the best choice for every recipient. If my family already knows how to receive money through Western Union, that familiarity may outweigh a competitor’s cleaner interface.
One non-obvious trade-off is that a familiar brand can encourage overconfidence. I would not assume that a well-known name means I can skip the final review. The app makes sending accessible, but the user still has to confirm the details and decide whether the transaction terms suit the situation. The safer workflow is to compare the displayed outcome with the amount and timing agreed with the recipient before completing anything.
Why it can remain useful month after month
The app’s lasting value comes from repetition. If I send money every month, removing even a small amount of friction from that routine is worthwhile. I can keep the task on my phone, use a familiar sequence, and avoid rebuilding the process from scratch each time. That is more important to me than decorative features or a particularly exciting first impression.
Regular users should create a personal pre-transfer routine. I would check the recipient’s details, confirm the amount, read the final summary, and make sure the phone is secure before sending. I would also keep a simple record of the date, amount, and purpose in my own financial notes. That record helps me reconcile family support with my monthly budget and prevents the app from becoming the only place where I remember what I sent.
Another useful habit is separating urgent transfers from scheduled financial planning. The app can make an immediate transfer feel easy, which is helpful in a genuine emergency but risky if it encourages impulsive decisions. I would set a monthly remittance amount before opening the app, then treat anything extra as a separate decision. That keeps the convenience of mobile sending from quietly replacing a budget.
The app is also well suited to people who travel or relocate. Someone working abroad may need to send money home while moving between cities, and a mobile workflow is more flexible than relying on a nearby service counter. The benefit is strongest when the sender already understands the recipient’s needs and has a stable process for checking each transaction.
Western Union Apps has maintained this product across a long period: it was released on August 18, 2011, and continues as version 16.4. I read that longevity as a sign that the app is intended to support an established financial habit, not just a short promotional campaign. It does not mean every update will feel important to every user, but it makes the product feel like a continuing tool rather than a temporary experiment.
The maintenance burden of a money-transfer app
Maintenance here is less about constant customization and more about staying disciplined. I need to keep the app available on a compatible device, protect access to my phone, and pay attention to the details shown during each transfer. Because this is a finance app, I would not treat updates and account access casually. I also prefer using a private connection and avoiding a rushed transfer on a shared or unfamiliar device.
The app itself may reduce the physical maintenance involved in sending money, but it does not remove administrative work. Recipient information can change, family circumstances can change, and the amount I send may need to change with my budget. I would review recurring assumptions periodically instead of sending the same amount automatically in my head just because the previous month looked similar.
A useful maintenance tip is to verify the recipient before an unusual transfer, even if the person is familiar. For a normal monthly payment, I might recognize the details immediately; for a new destination or a larger amount, I would slow down and check again. This is a small habit, but it addresses the most serious weakness of convenient financial apps: a mistake can be completed quickly too.
Another consideration is device age. The minimum operating system is Android 8.0, which covers many users but still makes compatibility worth checking before relying on the app for an urgent transfer. I would install and test access before travelling, not after arriving somewhere with limited connectivity or limited alternatives. That is especially important for people who use an older phone as a backup.
The app is free to download, but I would not confuse that with every transfer being cost-free. The meaningful financial comparison is the final amount and the conditions presented for the specific transaction. I would read the displayed details instead of choosing a service based only on the download price. This is one of the clearest cases where a free app can still require careful cost awareness.
What may cause fatigue over time
The first source of fatigue is repetition without enough attention. Sending money every month can become automatic, and automatic behavior is exactly when I am most likely to overlook a changed recipient detail or a different transfer summary. The app’s convenience is valuable, but it can also make the task feel less serious than it is.
The second source is comparison. A regular sender may eventually wonder whether a bank, another remittance service, or an in-person option would produce a better result for a particular destination. Western Union Send Money Now is convenient, but convenience is only one part of the decision. If another service consistently fits my recipient’s preferred delivery method or gives me a better overall outcome, loyalty to one app would not make sense.
The third is the emotional pressure around urgent requests. A relative may need money immediately, and a fast mobile workflow can make me feel that I should act before checking. My rule would be to confirm the request through a trusted channel if anything seems unusual, then review the transfer details without rushing. The app can help me send; it cannot determine whether the request itself is genuine.
Some users may also grow tired of maintaining a separate tool for one financial task. If I only send money once or twice a year, a bank service or a local agent may be simpler because I do not need to keep another app in my routine. The strongest long-term case is for people with repeated international remittance needs, not occasional users who are trying to minimize the number of apps on their phone.
I would also skip it if I expect a fully managed experience in which the service chooses the best route, explains every financial implication in plain language, and handles my budgeting automatically. This app is a sending tool. It supports the transaction, but I remain responsible for checking the information, understanding the result, and keeping my own records.
My long-term verdict
After the novelty fades, Western Union Send Money Now still has a clear reason to stay installed: it turns international remittances into a repeatable mobile task. I value it most when I already know whom I am sending to, how much I intend to send, and why the transfer is needed. In that situation, the app’s focused purpose is more useful than a sprawling financial dashboard.
I would recommend it to families supporting relatives abroad, workers who regularly send money home, travellers who need a mobile option, and anyone who prefers managing a remittance without visiting a physical location. The free download and Everyone rating make it approachable, while support for Android 8.0 or later keeps it available to many existing devices. The strong user response and more than ten million installs add confidence that it is a mature choice.
I would be more cautious about recommending it to someone who sends money very rarely, wants all banking activity in one app, or chooses strictly by the lowest total cost. In those cases, comparing the final transfer terms with a bank or another remittance service is sensible. A different option may be better if it is more convenient for the recipient, easier to reconcile with the sender’s finances, or more suitable for the particular destination.
My best advice is to build a two-minute checking ritual around the app. Confirm the recipient, decide the amount before starting, read the final summary, and record the transaction afterward. That routine protects the long-term value of the app because it keeps convenience from becoming carelessness. It also answers the practical question many new users have: yes, the app can become part of a dependable monthly habit, but only if the habit includes verification.
In the end, I see Western Union Send Money Now as a practical, focused finance app rather than an all-purpose money manager. It earns lasting space on my phone when international transfers are a recurring part of life. Its main weakness is not that it lacks novelty; it is that no app can eliminate the need for careful financial judgment. Used with that understanding, it is a useful way to send money worldwide and a reasonable recommendation for the right kind of user.
Pros
- Send money internationally from your phone at any time.
- Multiple delivery options, including bank accounts and cash pickup.
- Transfer tracking helps you monitor the payment status.
- Wide global network of agents supports cash collection.
- Recurring recipients can be saved for faster future transfers.
Cons
- Exchange rates and fees can vary significantly by destination.
- Some transfers require identity verification and extra documentation.
- Cash pickup availability depends on local agent opening hours.
- Transfer limits may restrict larger payments or frequent sending.
- Refunds and cancellations can take time after a transfer is submitted.
FAQs for Western Union Send Money Now
What is Western Union Send Money Now, and how does it work?
Western Union Send Money Now is the company’s mobile money-transfer service for sending funds to people in other countries or locations. After creating an account, you can enter the recipient’s details, choose a payment method, review the exchange rate and fees, and submit the transfer. Depending on the destination, the recipient may collect cash, receive money in a bank account, or use another supported delivery option.
Is Western Union Send Money Now safe to use?
The app includes account security features and transaction tracking, but users should still take precautions. Always download it from the official Google Play Store or Apple App Store, verify the recipient’s information carefully, and never send money to someone you do not know. Western Union transfers can be difficult or impossible to reverse once collected, especially when sent as cash pickup.
How much does it cost to send money with the app?
The total cost depends on several factors, including the sending country, destination, transfer amount, payment method, delivery method, and current exchange rate. The app normally displays the applicable transfer fee and the estimated amount the recipient will receive before you confirm payment. It is worth comparing the final received amount rather than looking only at the advertised fee.
How long does a Western Union transfer take to arrive?
Delivery time varies according to the selected service and destination. Some cash-pickup transfers may become available within minutes, while bank deposits and other delivery methods can take longer because of banking hours, weekends, holidays, identity checks, or local regulations. The app provides an estimated delivery time and a tracking number, but the estimate is not always a guarantee.
What information and identification are required to send or receive money?
Requirements differ by country, transfer amount, payment method, and delivery option. Senders generally need an account, valid personal information, and an accepted payment method. Recipients collecting cash usually need the tracking number, the sender’s details, and a valid government-issued identification document that matches the transfer information. Additional verification may be requested for security or regulatory reasons.

Western Union Send Money Now
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via customerservice@westernunion.com, visit https://www.westernunion.com/us/en/home.html, or review their https://www.westernunion.com/us/privacy-statement.










